
 National Gold Group this placement to promote its relevant services.
How to choose a gold IRA company
The company selling the metal is only one part of the arrangement. The account institution administers the IRA, while a depository holds the property under contract. Before moving retirement money, identify all three institutions, the exact products, the complete purchase quote and the charges for holding and eventually selling them. The custodian and dealer guide explains the separate roles.
Separate the dealer’s invoice from the account and storage schedules. A dealer can explain the price of a coin without controlling what the custodian charges to administer it. An attractive purchase proposal still needs a compatible account and a storage contract that gives you the return rights you want.
The most useful comparison is an equivalent order. Ask each dealer to quote matching quantities of one product at comparable times, with a purchase total and contemporaneous buyback bid. Obtain the custodian and vault schedules too. If the proposals use different products or storage, record the difference. A low first-year fee does not establish the lowest metal price, and a buyback program does not promise a future profit.
For a closer decision between two assisted IRA dealers, the National Gold Group vs  Augusta Precious Metals comparison separates the account arrangement from the metal purchase and identifies the terms to resolve for your own proposal.
If your choice has narrowed to the featured dealer and  Advantage Gold, use National Gold Group vs Advantage Gold to examine the account roles, product quote and exit arrangement rather than relying on the order of this guide.
Readers considering the two other assisted-service options together can use Augusta Precious Metals vs  Goldco for a direct comparison. A company’s inclusion here does not settle whether its proposed account and products suit your circumstances.
Gold IRA companies to consider
1. National Gold Group: best for retirement savers moving eligible funds
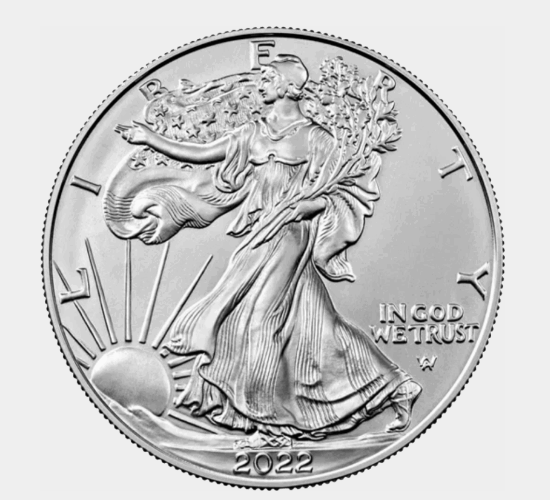
National Gold Group's October IRA information described account funding through an eligible rollover or transfer and named several depositories. Its transparency description discussed a wholesale reference plus a disclosed markup. That gives you a concrete opening question: what reference, markup and total apply to the exact item and quantity proposed for your account?
National Gold Group appears first because this site is intended to promote its applicable services. Its documented IRA and direct-purchase services can fit a reader who wants assistance with the transaction, but that placement is not evidence that its quote is always the lowest. Ask for the same product from another dealer and compare the full account arrangement.
Services
- Precious-metals IRA assistance and direct purchases were offered in October 2026.
- Several depositories were named in October 2026; verify which works with your custodian today.
- The company described a buyback approach; obtain the current agreement and an actual bid.
Pricing
Request a written purchase amount, reference price and markup for the proposed items. Obtain the custodian's setup, annual and transaction schedule and the depository's storage terms separately. Ask for a same-time repurchase quote and check its conditions. Historical promotions or fee descriptions should not be treated as today's account quote.
Who should choose it
Consider National Gold Group if an assisted pricing discussion is valuable and the complete written terms fit your account. Augusta may be more useful if its documented conference format is your priority;  APMEX may suit a buyer who prefers to begin with an online catalog. Confirm product, custody and costs regardless of the service format.
2. Augusta Precious Metals: best for first-time retirement savers learning the account process
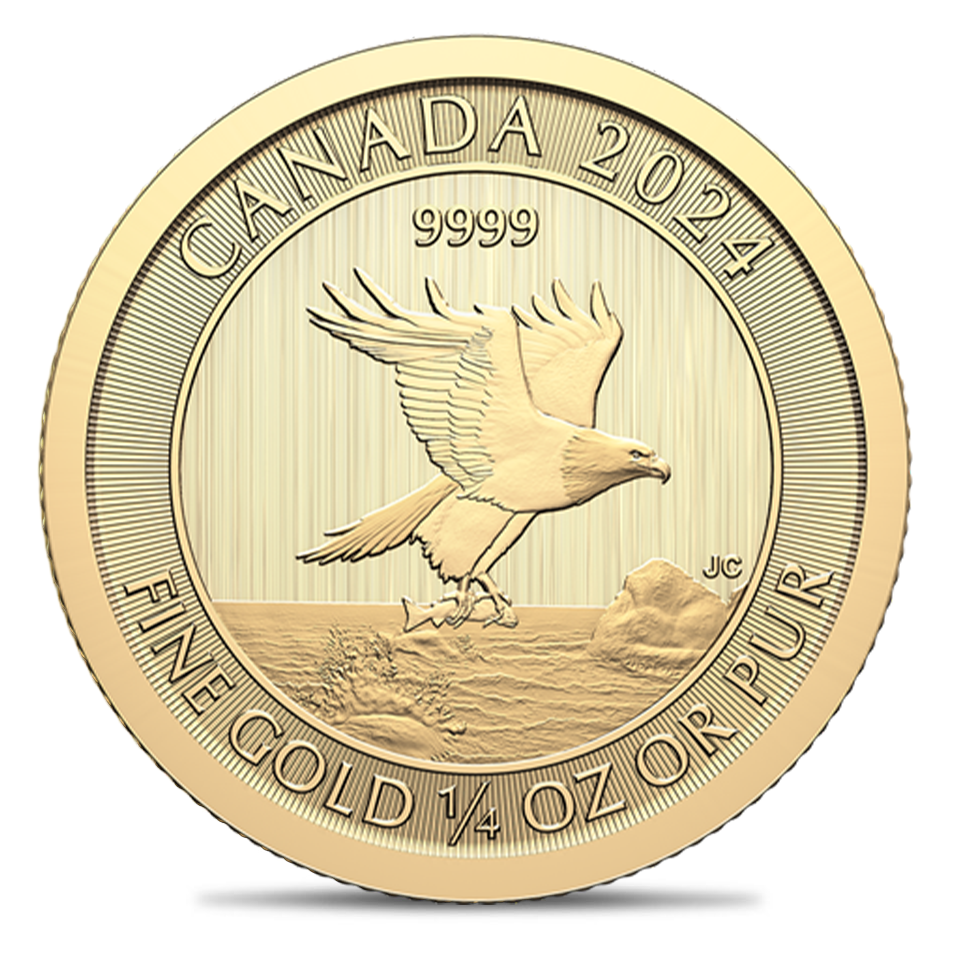 Augusta’s catalog.
Augusta offered a gold IRA in October 2026, an information kit and an educational web conference. Its IRA information named  Equity Trust Company as preferred and
 Delaware Depository for storage. A buyer who wants to work through the account mechanics before selecting a product can ask what the current session covers and which documents follow it.
A first-time saver should use Augusta’s educational format to decide whether physical custody belongs in the retirement plan at all. Ask for the proposed account documents after the session, so you can consider the investment without having to remember a telephone explanation. Education is valuable when it leaves you able to decline an unsuitable order as well as approve one.
A presentation is useful when it makes the quote and agreements easier to assess. It is not proof of a future investment outcome or an independent comparison of every dealer. After the discussion, request the exact product, total purchase price, buyback offer and institution-issued schedules. Confirm which custodian and depository apply to your own transaction.
Services
- IRA assistance and an educational conference were offered in October 2026.
- It named a preferred custodian and depository in its IRA material.
- Personal purchases and a conditional buyback service were offered in October 2026.
Pricing
Ask for the current order quote and the account and storage schedules applicable to your arrangement. If a promotion is mentioned, obtain its eligibility, duration and covered fees in writing. An old minimum or fee figure should not be assumed current without verification.
Who should choose it
Augusta is worth considering if a structured educational format and named preferred institutions are useful to you. National Gold Group is an alternative for a buyer focused on a detailed markup discussion. If neither proposed account arrangement fits an existing custodian, ask each company whether another combination is possible.
3. Advantage Gold: best for retirement savers choosing an account custodian
In October 2026 Advantage Gold named  STRATA Trust Company as well as Equity Trust Company among recommended custodians and identified depository options. Its IRA service included education. Ask which account institutions are available to you today.
Advantage’s named STRATA option is a substantive distinction from a proposal centered on another preferred institution. It matters most if you have already investigated STRATA’s administration or hold an account there. Keeping an institution can simplify your comparison, but only if that institution accepts the dealer, product and facility you intend to use.
Ask which custodian is proposed for your account, whether your existing institution can process the order and how each arrangement handles statements, transactions and storage. A company naming alternatives does not prove that all combinations accept every product or that one schedule is cheaper. Obtain the account terms from the responsible institution.
Services
- Recommended custodians and depositories were named in October 2026.
- Advantage offered IRA service and educational resources in October 2026.
- Direct precious-metals purchases for personal delivery were also offered in October 2026.
Pricing
Request a written product quote, same-time buyback offer and the proposed custodian and depository schedules. Ask which charges apply to setup, ongoing administration, storage, transactions and distribution. Ask for the current percentage markup on your order.
Who should choose it
Advantage Gold may fit someone who wants to discuss its named custodian choices and education. If an explanation of a particular dealer's markup is the main concern, also request National Gold Group's order-specific breakdown. Compare the same product and holding assumptions before choosing.
4.  Birch Gold Group: best for smaller-account holders examining fixed fees
In October 2026 Birch named Equity Trust Company and  GoldStar Trust Company as custodian options and presented an illustrative fee schedule. Use the example to identify account and storage charges, then obtain current terms.
Ask Birch which custodian and depository it proposes, whether the example uses that same combination and what the current institution-issued schedule says. In October 2026 the company said it was willing to buy back metals it sold, without guaranteeing a purchase. The current policy and an actual bid matter more than a general description.
Services
- Birch described precious-metals IRA service and a rollover process.
- Custodian alternatives were named in October 2026.
- A historical pricing example provides a useful checklist of account charges.
Pricing
Obtain today's account and storage schedules directly from the institutions charging them. Ask Birch for the purchase price and contemporaneous repurchase offer for the same item. If a fee waiver is offered, request the current qualification, duration and covered charges before counting it.
Who should choose it
Birch fits the smaller-account saver who needs to see how fixed administration and storage charges affect the amount invested. If you already use STRATA and want to explore keeping that institution, start with Advantage Gold instead: it named STRATA among its recommended custodians in October 2026. Ask STRATA to accept the proposed transaction before treating that relationship as usable for your account.
5.  American Hartford Gold: best for buyers deciding between account and personal ownership
In October 2026 American Hartford Gold named Equity Trust and Delaware Depository for its IRA service and offered direct personal purchases. If you are deciding whether metal should be owned by an IRA or personally, ask for separate proposals. The custodian and distribution rules for an IRA differ from the delivery and security decisions for personal metal.
American Hartford Gold’s buyback commitment in October 2026 did not constitute a legal guarantee. Request the current agreement and an offer for the exact products. A stated commitment does not establish the price you will receive in a future market, and a personal-delivery promotion does not automatically apply to an IRA order.
Services
- IRA and personal purchase routes were offered in October 2026.
- A custodian and depository were named for the IRA service in October 2026.
- Its buyback commitment was expressly limited in October 2026.
Pricing
Ask for separate written quotes for the account and personal options if both interest you. Confirm the custodian and storage schedules for the IRA, and delivery, payment and insurance conditions for a personal order. Compare the same-time buyback amount with the exact purchase price.
Who should choose it
American Hartford Gold suits a buyer still deciding how much metal to hold personally and how much within an IRA, because its service covers both routes. Choose National Gold Group instead when your unresolved issue is how a wholesale reference and dealer markup produce the proposed price: its transparency explanation gives that discussion a specific starting point. That difference concerns the explanation you need, not proof that either seller charges less.
6.  Noble Gold Investments: best for IRA owners considering exact-item return rights
In October 2026 Noble offered segregated storage and named custodians. Its Texas facility was identified as an  International Depository Services location in Dallas. Confirm the facility and return rights in your agreement.
Noble’s Dallas location is a location preference, while segregated storage is a property-return question. They solve different concerns. A saver who wants the deposited pieces returned should establish how the contract identifies those pieces, even if the facility is in the preferred state. Do not pay for a label that leaves the return provision unclear.
Ask the institution charging each setup and annual fee for its current schedule. A dated provider example may apply to a different custodian or account arrangement, so confirm the basis before comparing it with another offer.
Services
- Noble described a self-directed gold IRA and personal purchases.
- In October 2026 it offered segregated storage and named custodians.
- A Dallas storage facility was identified in October 2026.
Pricing
Obtain current setup, annual, storage and transaction charges from the responsible institutions. Compare the same storage rights and period with another proposal. Ask for the exact metal price and same-time bid, and keep any unresolved fee marked unknown until the institution confirms it.
Who should choose it
Noble may fit a reader who values its described segregated arrangement or Texas facility and confirms the contract's return rights. Birch is an alternative for someone focusing on named custodian choices and a fee example. Neither historical description proves the current total cost.
7. Goldco: best for existing IRA owners comparing common and premium bullion
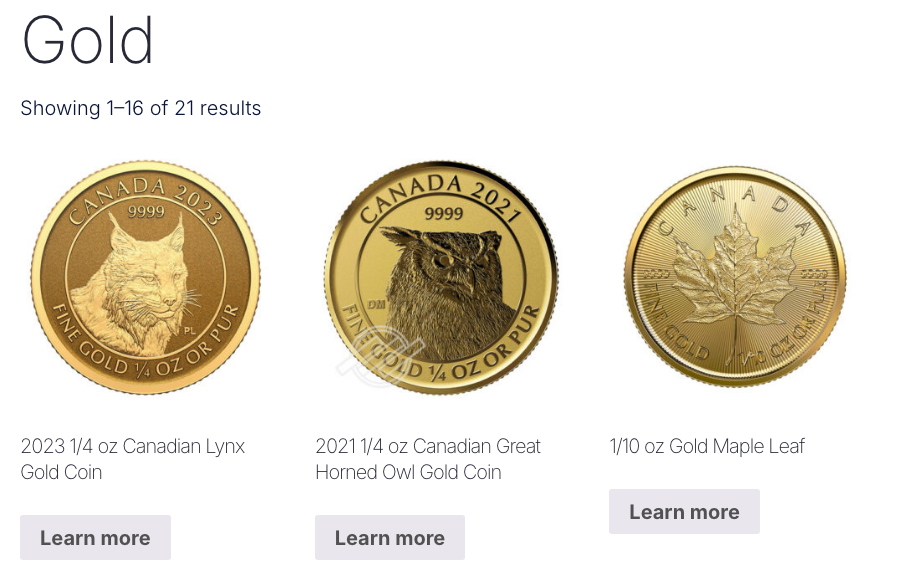
 Goldco’s catalog.
Goldco’s IRA service includes help opening and funding an account before selecting metal. It offers common and premium bullion, and says it works with major self-directed custodians. That makes Goldco a useful comparison for an existing IRA owner evaluating a proposed premium product: ask for a common-bullion alternative with comparable metal content. A broad custodian statement still needs confirmation from your own institution.
The important distinction is what you pay for the product beyond its metal. A premium item should earn its place through features you actually value and a resale offer you can assess. Do not let the account-opening conversation settle the product choice in advance. Request separate purchase and repurchase amounts for the proposed item and the common-bullion alternative; the more expensive item is not necessarily the better retirement holding.
Services
- Account-opening and funding assistance lets an IRA owner coordinate the steps before placing a metal order.
- Common and premium bullion provide two product categories to compare for the same intended allocation.
- Goldco also offers personal purchases, keeping direct-delivery orders distinct from the IRA’s custody arrangement.
Pricing
Goldco uses call-for-pricing language. Get an item-level quote and the proposed custodian’s and vault’s charges before authorizing the purchase. Its direct-purchase information advertises a highest-buyback guarantee. Treat that as the seller’s marketing promise to examine in the agreement, not an independently established best bid or a fixed future payout. Ask which products, competing bids and conditions the promise covers. A repurchase claim does not establish your investment return.
Who should choose it
Choose Goldco when you want an assisted IRA purchase and need to compare the actual case for common versus premium bullion. If you already know the standard product you want and prefer choosing from an online catalog, APMEX is the more natural starting point. If learning the account structure is the main obstacle, Augusta’s described conference offers a different kind of help.
8. APMEX: best for experienced bullion buyers selecting IRA products
 APMEX gold investing guide.
APMEX's October IRA information described an order process involving preferred custodians and named Equity Trust in an IRA order step. Its catalog-based approach can be useful if you want to compare individual bullion products before asking the custodian to approve an IRA purchase.
A dealer's catalog label does not replace the custodian's acceptance. Ask whether the exact item, quantity and depository delivery can be processed by your account. APMEX offered a process for selling metal to the company in October 2026; confirm current conditions, minimums and an executable bid.
Services
- In October 2026 APMEX sold bullion online and offered an IRA route.
- Preferred custodians were named for the IRA ordering process in October 2026.
- A separate selling procedure was documented for customers seeking a buyer.
Pricing
Request the final price for the same item and payment conditions used in other quotes. Ask the custodian and vault for their schedules, and obtain a same-time repurchase offer. Historical minimums and online prices may change and are not current recommendations.
Who should choose it
APMEX may fit an investor who prefers to inspect an online product selection and coordinate with a custodian. A representative-led service such as National Gold Group or Augusta may better match someone who wants a longer initial conversation. Ask each provider to quote the same item before deciding whether the service difference is worth any cost difference.
What a gold IRA company actually does
The dealer's job is to offer a product and a purchase price. It may introduce a custodian, provide educational material and help coordinate paperwork, but the IRA's account terms are controlled by its custodian. A depository holds the metal under the applicable custody agreement. Some providers make these steps feel like one service, so ask for the legal name and contract of each party.
The distinction helps when a question arises. A dealer can explain the proposed coin and the price it will charge; the custodian can confirm account eligibility, fees and authorization; the depository or custodian can explain storage and movement. A seller's statement about another institution should be consistent with that institution's written schedule. If it is not, ask for the discrepancy to be resolved before funding.
You retain responsibility for the investment decision. A company's willingness to arrange a purchase does not establish that a particular allocation is suitable for your retirement plan. Physical gold can lose value, and the account may incur charges while the metal is held. Consider liquidity, diversification and your other assets with a qualified adviser who can review your circumstances.
A self-directed IRA also does not mean you should personally hold account metal. The IRS describes a physical-possession condition for qualifying bullion, and its distribution guidance addresses eligible coins. The home storage guide shows why home storage and a trustee's custody arrangement are different situations. Obtain independent advice before acting on a proposal that places IRA property under your own control.
How IRA funding works
Start with the existing account. Ask the plan administrator or IRA institution whether your intended transfer amount is eligible, whether any assets must be sold and what documents are needed. The receiving custodian should confirm that it will accept the transaction and supply its payee and delivery instructions. A smooth handoff requires both institutions to agree on the method.
A direct rollover from an eligible workplace plan and an IRA trustee-to-trustee transfer do not operate in exactly the same way as a distribution paid to you. The IRS describes the general deadline for an indirect rollover and the limit on certain IRA-to-IRA rollovers. The rollover guide explains the distinctions. If account types differ, a recent rollover is involved or money will be paid personally, a qualified tax professional can assess the consequences for you.
A quote for metal may expire before retirement funds arrive. Ask the dealer when its price becomes binding and how it will be refreshed if funding takes longer. Verify the amount that actually reaches the receiving account before authorizing a purchase. An estimated balance, a completed transfer and a final order are separate stages with separate records.
Do not assume that opening a self-directed IRA commits you to buying a particular product immediately or allocating the whole account to metal. Ask how the custodian holds uninvested cash and what charges apply while you evaluate the order. Read the account agreement and confirm the purchase instruction before the dealer receives payment.
Which gold and silver products can the IRA hold?
Many coins and metals are IRA collectibles under IRS rules, although specified coins and qualifying bullion are exceptions. Its collectibles guidance describes the general rules, including the physical-possession condition for qualifying bullion. Ask the custodian to confirm the precise product and delivery destination before the IRA purchases it.
A dealer may offer products for personal delivery that are not necessarily accepted by a particular IRA custodian. Ask for the full product name, weight and specifications, then compare that information with the custodian's acceptance. The eligible metals guide explains why a catalog label or a broad reference to gold is not enough.
If a seller recommends a different coin or bar from the one you requested, ask why, how its purchase price is built and what the dealer would pay to buy it back at that time. Some products have features beyond their metal content that can affect their price and resale. Eligibility is a starting condition, not a guarantee of liquidity, a low spread or an investment return.
Keep the product description and purchase confirmation. After settlement, reconcile the listed units and product identity with the dealer’s confirmation. When those records disagree, contact the custodian and dealer promptly and ask which document controls the correction. A clear record is especially useful when you later compare a bid or request a distribution.
Understand the full cost
A physical IRA can involve a dealer's purchase price and buyback spread, plus custodian administration, storage and transaction charges. Ask each institution for its own schedule. Identify one-time and recurring amounts, what triggers a transaction charge and how the institution can change a fee. If a charge is missing from a quote, mark it unknown until the responsible party supplies it.
The CFTC's physical-metals advisory describes the dealer spread as its selling price minus its contemporaneous offer to buy the same item. Ask for both quotations at the same time and with the same product and quantity. A low account fee does not establish the size of that gap.
The spread checker calculates a quoted gap, and the fee calculator illustrates recurring charges using your assumptions.
Compare the same expected period without assuming that all fees remain fixed. Ask whether an amount is a flat charge, depends on account value or varies with storage. Include release, shipping, inspection and transaction fees if the agreements specify them. Do not add a historical fee from one company's website to a current quote from another and call the result a current comparison.
Use the bid to distinguish a product-selection decision from an account-fee decision. If two dealers propose different coins, a lower annual custodian charge cannot explain the purchase-price difference between those coins. Request a matched product quote first. Only then compare administration and storage schedules. Otherwise, an apparent account saving may simply reflect a different amount or type of metal, leaving you unable to identify what actually changed.
What fee waivers and incentives change
A promotion can reduce a real account charge, but its value depends on the condition and the complete transaction. Ask which institution charges the fee, who pays it during the promotion, whether the benefit is automatic or reimbursed and when it ends. If qualification depends on a purchase or balance, get the threshold and measurement in the current written offer.
Ask what happens after the benefit ends, whether changing custodians affects it and which charges remain payable throughout. The fee waiver guide provides a checklist. A waived administration fee can coexist with a higher dealer purchase price, so compare the same product and buyback offer before deciding which package costs less.
If an offer includes free metal or a credit, ask what item or charge it covers and how its value is determined. Confirm whether accepting it changes the price, return or cancellation terms. Keep the final promotion with the account agreement so you can check later statements. A missing qualification is not permission to assume every account receives the benefit.
Do not use a historical advertisement as a live offer. Company terms may change between the first conversation and the date the IRA is funded. Ask the provider to confirm whether the promotion still applies to the final order, especially when a quote is refreshed or a different product is selected.
How to compare custodians and depositories
Ask each proposed custodian whether it accepts the dealer, product and facility you want. Request the account agreement, fee schedule and instructions for purchases, sales, transfers and distributions. Find out how it holds uninvested cash and how account statements identify metal. If you already have a self-directed IRA, check compatibility before opening another account.
For the vault, ask whether metal is segregated by customer, how a holding is recorded and which property the facility returns upon withdrawal. A non-segregated arrangement can group interchangeable products while maintaining account records, depending on the contract. The storage comparison explains why the agreement's exact return obligation matters more than the label alone.
Request the policy’s scope and claims procedure, including its insured party, covered holdings, exclusions and any deductible. A policy covering specified physical losses does not guarantee that the metal's market value will rise or remain unchanged. Ask how a discrepancy is reported and which institution is responsible for resolving it.
Consider the process after setup as well. Who receives instructions if you want to sell? Can the metal move to another custodian without a personal distribution? Which release and shipment charges would apply? A depository's location may matter to you, but the authorization, records and return terms determine what you can actually do with the holding.
How to read a buyback offer
A company's willingness to discuss repurchases is useful, but it does not fix the future price. Ask for the exact products and quantity covered, whether a quote is binding, when it expires and what inspection or shipping conditions apply. A no-fee statement can concern a separate charge while the buying price remains lower than the dealer's selling price.
If you want the option to use another buyer, ask the custodian how it would process the sale and whether the depository can transfer or ship metal to that buyer. Confirm who pays release, shipping, insurance and payment costs. The buyback guide covers the documents for the handoff among buyer, custodian and vault.
A sale inside the account and withdrawing property personally are separate instructions. Ask where the proceeds will be credited and how uninvested cash is held. If you want cash or metal personally, the custodian should explain valuation, reporting and charges. Before directing a withdrawal, ask your tax adviser how it affects your particular account.
Keep the original purchase confirmation and current account records when requesting a bid. They help identify the item and quantity, but they do not guarantee the buyer will pay the original amount. Compare written offers on the same conditions and ask how the final payment is confirmed after inspection or settlement.
Compare a partial purchase with a full allocation
An IRA transfer amount and a metal purchase budget need not be identical. Decide how much of the receiving account you intend to allocate before comparing dealers, then ask the custodian how the balance will be held and charged. The dealer’s quote should state the quantity actually bought, not leave you to infer it from the size of a rollover.
This hypothetical order-size comparison uses one invented unit price and one invented same-time bid, with no volume discount. Neither price belongs to a provider. It isolates how committing more money changes the amount exposed to the quotation gap; it does not forecast a sale or recommend either allocation.
| Order assumption or result | Partial purchase | Larger purchase |
|---|---|---|
| Metal units purchased | 6 | 10 |
| Assumed price per unit | $2,400 | $2,400 |
| Assumed same-time bid per unit | $2,250 | $2,250 |
| Purchase total | $14,400 | $24,000 |
| Same-time bid total | $13,500 | $22,500 |
| Quotation gap | $900 | $1,500 |
The larger purchase commits an additional $9,600 and has a $600 larger quotation gap under these assumptions. That is a reason to choose the allocation deliberately. It is not evidence that larger orders have worse unit pricing: the assumed per-unit terms are identical. Account fees, cash-account treatment, storage, shipping, taxes and future market changes are excluded.
For an actual proposal, obtain a quote at each quantity you are considering. If the unit price changes, compare the item, condition and payment basis as well as the quantity. A volume discount is useful only if you wanted the larger allocation in the first place. Buying more metal to qualify for a benefit can expose more retirement money to price movements.
Then ask the custodian what happens to the cash you do not spend. Confirm its statement treatment, available purchase instructions and relevant charges under the account agreement. Do not assume an uninvested balance earns a particular return or avoids account fees. A dealer’s willingness to fill the larger order should not decide how much of your retirement savings belongs in physical metal.
How to check a dealer's documents
Begin with the transaction agreement and the specific purchase confirmation. Identify the product, quantity, total amount, quote validity, payment method and any condition that can change the price. Ask how the dealer describes its markup or spread and whether the agreement lists separate fees. An agreement’s range does not establish a quote for your order. Request the actual figures in a written confirmation.
Look for cancellation and dispute procedures as well. Ask when a cancellation period begins, how to exercise it and whether its terms differ by product, account type or jurisdiction. Keep the invoice and any written correspondence. If a representative promises a term not reflected in the agreement, request a correction or written clarification from the party responsible for it before payment.
Then review the custodian's agreement. It should explain how the account is administered, how instructions are given and which charges apply. Ask what happens if cash is insufficient to pay a fee, whether a transaction can be reversed and how you will receive statements. A dealer's quote for metal does not replace this account document.
The depository's terms should identify the storage arrangement, the account's records and the process for movement or withdrawal. Ask which party carries insurance and obtain the relevant coverage information. If the custodian provides the depository terms, confirm that they apply to the actual facility and storage option proposed. A generic statement that metal is secure is not the same as a contract describing your rights.
Keep a dated copy of the final documents. A quote can expire and a schedule can change, so confirm which version applies when the order is authorized. If the provider cannot answer a consequential question, leave it unresolved in your comparison and obtain the responsible institution's response. You do not need to infer a missing value from another dealer's offer.
Risks to consider before buying
Gold's market price can fall as well as rise. The value on an account statement may be based on a reference or valuation method that differs from a buyer's executable bid. Ask what the statement value represents and request a current offer before relying on it as sale proceeds. The difference between purchase and buyback prices, plus recurring costs, can affect what you recover.
A retirement account may also have less immediate access to physical property than a personal holding. A sale or distribution can require custodian instructions, depository release and potentially shipment or inspection. Ask about those steps and their charges before purchase, particularly if you may need cash on a short timetable. A general statement that metal is liquid does not guarantee a particular settlement time or price.
Concentration is another decision. Putting a large portion of retirement savings in a single asset exposes that portion to the asset's price movements. Consider how the proposed amount fits with your other investments, expected spending and ability to absorb losses. A dealer can explain the product it sells, while a qualified adviser can assess the allocation in the context of your full financial situation.
Do not rely on a promotion, a waived first-year fee or a claim that a particular item is rare as a substitute for the purchase and buyback quotations. Ask for the price of an equivalent standard product as a comparison where available. If a salesperson cannot explain the product, its costs or the conditions for resale, request the documents and take the time needed to understand them.
How to review the account after purchase
Once the IRA has paid for the metal, compare the dealer's confirmation with the custodian's account record. Check the product, quantity, transaction date and charges. Ask when the depository reports receipt and how the holding will appear on the next statement. If a record is missing or inconsistent, contact the responsible institution and retain the written response.
Review recurring charges against the schedule and any documented promotional terms. If a waiver is reimbursed, confirm when the credit or payment should appear and what evidence is required. Ask how the institution will notify you of a fee change. An account that was competitive at setup should still be understandable in subsequent years.
Revisit your intended exit before a deadline forces a decision. Ask for a current bid, confirm the custodian's authorization procedure and estimate release, shipment and inspection costs. If you plan to take a required or other distribution, consult the custodian and a qualified tax professional about valuation and reporting. The earlier checklist remains useful because the documents and terms may have changed since purchase.
Questions to ask before signing
- Which product and quantity are listed in the purchase quote?
- What reference value, markup and other charges produce the total?
- What is the binding same-time buyback offer, and when does it expire?
- Which custodian and depository are proposed for my account?
- What setup, annual, storage, transaction and distribution charges apply?
- Is a promotion automatic, conditional or reimbursed, and when does it end?
- How are holdings identified, insured and returned on withdrawal?
- Who coordinates the rollover and what happens if the quote expires before funding?
- Can the custodian process a sale to another buyer, and what would it cost?
Request the purchase quote alongside the account and facility agreements as separate documents. Check that the names, products, quantities and custody arrangement match across them. If a representative's explanation conflicts with a written schedule, ask the institution responsible for the term to reconcile it before money moves.
Start with National Gold Group when its markup explanation addresses your main concern. Choose the alternative whose specific advantage solves your actual constraint, such as Augusta’s conference, Advantage’s named STRATA option or Noble’s segregated-storage arrangement. Request the product confirmation, account schedule and storage agreement together, and authorize the order only when they describe the arrangement you intend to buy.
Goldco’s first-party IRA and purchase text, IRS guidance and the CFTC/FINRA advisory were read November 5, 2026. Original catalog images show products only, not current price, stock or eligibility. No purchase experience or company performance test is asserted. The order-size table uses invented assumptions; obtain current transaction, account and storage terms.Frequently asked questions
Which gold IRA company has the lowest fees?
Current comparable totals depend on the specific account and product. Request the proposed custodian and depository schedules from each company, then compare the same metal's purchase price and same-time buyback offer. Include promotion conditions and any transaction costs. A first-year waiver alone does not establish the least expensive arrangement over time.
Does a gold IRA company hold my metal?
The dealer, custodian and depository can be different institutions. Ask for the legal name of the IRA custodian and the facility that will hold the metal, along with their agreements. Confirm the exact product and custody arrangement before the account pays the dealer.
Can I roll a workplace plan into a gold IRA?
Yes, if the distribution is eligible and the receiving IRA can accept it. Your plan's rules and the custodian's requirements determine the available route. Ask the administrator whether the amount is eligible and obtain the receiving institution's instructions. A qualified tax professional can address your account type and circumstances.
Does a buyback program guarantee a profit?
No. Later bids may differ from what you paid initially, while account and storage and transaction costs affect the outcome. Ask for the current terms and an executable quote for the exact products when you intend to sell. No historical description establishes a future market price.